
Escape of water - Building a better future
Within new builds and major refurbishments plastic pipes are now the plumbing of choice but risk of water damage is often overlooked and insurers are looking to plug the gap, writes Richard Ayton-Robinson
Recent experience suggests 30% of all insurance claims in residential properties are due to damage caused by the escape of water. While fire caused by hot work associated with traditional plumbing methods was historically a serious risk for underwriters, modern practices involving plastic pipes have largely removed the fire risk during installation but replaced this with an increased risk of failure in usage. Add to this the recent credit crunch pressures encouraging corners to be cut to save money, and the risk of escape of water becomes more prominent and as increasing the cost for insurers.
Within new builds and major refurbishments, the move towards plastic piping with compression and push fit joints has provided benefits in terms of cost and ease of installation. It has also significantly reduced the fire risk associated with plumbing work, but the finished plumbing is not necessarily as robust as its metal predecessor.
Cutting corners
Plastic piping allows for much faster assembly times and when done correctly it will withstand the design pressures. However, time constraints associated with completion of new builds, a shortage of trained plumbers, and the economic pressures that contractors are under mean the job is not always done to the standard it should be. Workmanship failings mean that plastic pipes are not always cut to the correct size and so do not penetrate as far into the joint as they should, while hand tightened compression fittings are not always tightened enough to be effective. In the long term, poorly made joints will soon fail under pressure.
In the current economic climate, which has seen a collapse of the residential property market, more people are improving their existing properties instead of trying to move home. This trend has seen an increase in extensions and roof conversions, often to create additional en-suite facilities, bathrooms and wet rooms. Central heating installations are also being upgraded or replaced to meet the government's green agenda driven by the Energy Performance of Buildings Directive and the introduction of mandatory energy performance certificates for sales and lettings. All this recent activity makes the risk of a water escape claim much more likely.
It is not only the risk of resultant building damage that has increased; it is also the severity. Unlike traditional soldered joints, where a fault often resulted in a gentle oozing of water or a steady drip, if plastic pipes are not properly secured, these joints can separate completely, resulting in a sudden gush of water from an open pipe under mains pressure.
And if a failure occurs when the owners or occupiers are away from the property, a leak can be undetected for some time. At three-bar pressure, some 300 gallons of water would run from a 22mm pipe in 10 minutes.
The design of new buildings to higher standards of energy efficiency also has serious implications in terms of repair costs. Last year, flats and apartments accounted for more than 50% of all new build starts in the UK. The introduction of sound and thermal insulation in floating floor constructions has created gaps for water to penetrate and become entrapped, making drying out more complicated and protracted than in traditional buildings.
Weaker alternatives
Similarly, dry lining systems and insulated lightweight partitions may help speed up the construction process, but they are not as resilient to water damage as traditional masonry partitions and plasterwork. So a burst pipe can cause far more extensive damage than it would have done in the past.
Insurers must also understand that there is simply more plumbing in modern buildings. Pressurised wet heating systems, en-suite facilities and second bathrooms with pumped supplies to showers all present an increased risk.
To cite just one example of the destruction that can be wreaked by domestic plumbing, a five-storey block of flats was flooded with 700 litres of water a minute when a joint failed on a plastic pipe in the roof space. The water flowed for two hours causing damage to 30 flats; the worst affected tenants had to move into alternative accommodation, increasing costs by over 50%. The repairs took 18 weeks and the rest of the development must now be inspected to avoid further problems.
So how can the industry mitigate the risk from poor plumbing? The real difficulty for underwriters comes in gaining certification that plumbing work has been completed to a standard that can be relied upon. Although it is impossible to establish whether all joints have been adequately made, ideally an independent services engineer would do a visual inspection of the system as a whole to give an indication as to the general quality of the installation.
Delicate balance
However, getting such commitment upfront from developers and property managing agents is not easy. Indeed, if insurers' certification requirements are too stringent they face losing business in a market that is desperately competitive. So further work needs to be done between all the involved parties to ensure some meaningful certification of the plumbing is supplied and the costs involved are shared between the various parties.
Responding promptly to emergency situations can avoid massive repair costs. Providing emergency home assistance cover linked to a 24 hour helpline is one way of mitigating the loss. This is particularly important for managing agents dealing with blocks of flats where the cost of delay can be considerable.
People are becoming more reliant upon specialists to maintain and repair their homes. Many households lack the basic knowledge and skills to tackle maintenance tasks. It is no surprise, therefore, that when things go wrong, the public increasingly looks to their insurer to provide all the solutions.
Effective risk management of commercial property has proven to be a money saver in the long term. And insurers now need to work with the stakeholders to apply these principles to the domestic situation and push this higher up the priority ladder.
- Richard Ayton-Robinson is the home inspection services director at Cunningham Lindsey.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@postonline.co.uk or view our subscription options here: https://subscriptions.postonline.co.uk/subscribe
You are currently unable to print this content. Please contact info@postonline.co.uk to find out more.
You are currently unable to copy this content. Please contact info@postonline.co.uk to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@postonline.co.uk
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@postonline.co.uk
More on Personal
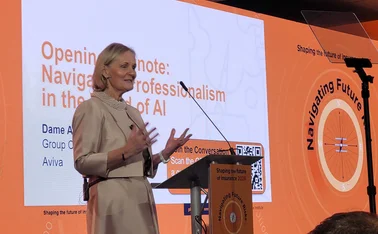
Aviva’s Blanc urges CII to ‘stay relevant’ amid AI boom
Aviva Group CEO Amanda Blanc has urged the Chartered Insurance Institute to lean into the “extraordinary opportunity” but stave off the real “threat of irrelevance” it faces as artificial intelligence continues to change the way the industry operates.
Aviva’s Morse is third HNW exec to join Euna
MGA Euna has hired the third Aviva high-net-worth private clients executive who left the provider back in May this year.
Sky Protect faces continued losses
Sky UK’s insurance arm has reported continued losses in 2025.
Throwback Thursday: Casualty of Eagle Star fallout
Insurance Post’s Throwback Thursday steps back in time to October 1991 to remind you what was going on this week in insurance history when Eagle Star’s restructuring caused a senior exit.
Insurers adapting windscreen cover prompts Defaqto ratings review
Insurers are changing the way they handle windscreen cover as more advanced technologies prompt new ways of thinking, according to Mike Powell, insight analyst for general insurance at Defaqto.
First Central confirms job loss total amid strategic reshuffle
First Central has confirmed the number of job losses as part of a strategic reshuffle revealed by Post last year.
How ChatGPT far from killing PCWs may help them grow
After the launch of insurance apps on ChatGPT, Scott McGee analyses where it has the upper hand on price comparison sites, where it needs to catch up, and how the future of distribution will settle.
UK pet insurance should adopt Swedish models to simplify claims
The Swedish pet insurance model could help streamline the UK claims process through the adoption of AI and automated claims handling, according to Wisentic Pets managing director Garry Nelson.