
Green Deal: Green living
With the Energy Act imposing new energy‑efficiency standards on commercially and privately let properties by April 2018, what do the changes mean for the insurance industry?
The Energy Act 2011 requires all commercially and privately let properties to meet minimum energy-efficiency standards by 1 April 2018. If a building does not meet these minimum standards, as rated via an energy performance certificate, then it will become unlawful to let that property.
As part of this the Green Deal scheme allows property owners to take out loans to make repairs or structural changes that are intended to result in energy savings, the cost of which is then passed on to a third party – the energy provider. Loans are repaid through energy bills because, in effect, they move with the property, rather than the person who took out the loan.
The government has already ploughed £200m into the scheme, but the implications of the legislation are only just starting to make themselves felt in the insurance industry. Large insurers appear to be taking up the green baton – but, according to one high-profile lawyer, there is a worrying lack of understanding among brokers as to what the legislation entails for their clients and, moreover, their clients’ businesses.
At the moment, it is expected properties will need an EPC rating of at least ‘E’ to comply. This is likely to be reviewed and increased in the run-up to 2018, with the cost of bringing buildings up to scratch UK-wide expected to run into the millions.
|
Number of buildings with energy performance certificates |
||||||
| Property type |
Total EPCs |
E-rated |
E% |
F-G rated |
F-G% |
|
|
Office |
641 |
158 |
25 |
151 |
24 |
|
|
Retail |
897 |
137 |
15 |
175 |
20 |
|
|
Industrial |
434 |
93 |
21 |
123 |
28 |
|
|
Warehouse/storage
|
410 |
73 |
18 |
130 |
32 |
|
|
Source: Resilts of EPC analysis for properties assessed by property services company DTZ to March 2013 |
||||||
Zurich has examined one reason for this level of expense. In its white paper The Impact of the 2011 Energy Act on property lettings, it said conservative estimates suggest 20% of commercial properties would not hit the standard required, meaning they would either have to be withdrawn from the market or be upgraded to meet the legislation, which would prove costly.
Mark Blanchard, property claims director at Zurich UK, says rebuild and reinstatement costs will affect the insurance market, and in the long run costs are most likely to be passed on via an increase in insurance premiums. “Across household and commercial property insurance, the cost of reinstatement is likely to increase as EPC ratings become more embedded into planning and construction requirements,” he says. “Any legislation that requires an insurer to put a customer in a better position post-loss typically comes at a cost, and could ultimately affect future premiums for customers.”
Blanchard hints current systems and processes may also need to be upgraded – which will also incur extra cost. “As green initiatives become the norm, there will be a need for insurers to ensure supply chains are able to respond to the new construction methods and materials,” he adds.
All this has made the Energy Act and the Green Deal a hot topic. DAC Beachcroft partner Nick Young says he has been “gobsmacked” by the amount of interest his briefings on the changes have received, saying: “People are extremely interested when I start to speak, but that’s because they haven’t heard of [the Act] before, or are not aware of its implications.”
Young says the Energy Act’s most immediate implication for brokers is that they must make sure all clients are insured for the correct amount. At the moment, if a building needs to be reinstated or completely rebuilt, the likelihood is that it falls short of the Act’s requirements in terms of insurance. “Of course, any rebuilding will be done with more modern materials, which are more energy efficient,” he says. “But making sure a building is compliant with 1 April 2018 is not a given.”
This means brokers need to make sure all their commercial clients – including private landlords – have insurance that makes any rebuilding or reinstatement meet the new legislation. Young continues: “Insurers are upping their game and we are seeing promotional material advising brokers about the need to make sure their clients are properly insured – but it is up to brokers to be proactive.
“The changes have a significant impact on the commercial and privately rented sector. It’s not just large pension funds that rely on income from renting out commercial property, it goes right down to Mr and Mrs Buy-to-Let with one or two properties.”
Steve Foulsham, head of technical services at the British Insurance Brokers’ Association, agrees: “In general terms, consumers and small businesses would need to keep their sums insured under review to ensure they are adequate for replacement and reinstatement in the event of a claim, which may need to be carried out in an energy efficient manner.”
Foulsham offers the example of solar panels – the installation of which would normally entail an increase to the reinstatement cost of a building. “Installers sometimes retain ownership of solar panels for a period of time, so it may be necessary to include their interest in the policy,” he advises.
This is where brokers and insurers come in – and Blanchard stresses the need to work together in order to help educate consumers on their changing insurance needs: “Understanding the demands of new legislation and complying with changing standards is not something commercial landlords should have to do by themselves. There is an important role for the insurance industry to play in terms of education, advice and improved policy wordings.
“At the moment, many standard commercial property policies have European Community and Public Authorities clauses that provide cover for additional costs of complying with European Community or UK building regulations. However, the cover only extends to meeting the minimum required level under current legislation – and this may not be enough [to comply with the Energy Act].
“Far-sighted landlords are looking to improve their properties well beyond the minimum standards and to introduce a degree of future proofing to their portfolio.”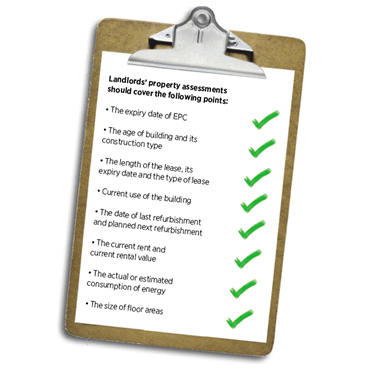
Early preparations
Some industry players are already helping forward-looking clients best prepare for the advent of the new requirements. Zurich, for example, has an energy performance and sustainable buildings clause – available as standard in most cases – which enables customers to improve the quality of the property and introduce new construction materials at the time of a loss, rather than simply reinstating what was previously in place.
As well as insuring their clients, brokers can also play a part in helping them get funding for any improvements necessitated, with Young saying brokers should be swotting up on initiatives such as Green Deal funding. He believes brokers need to go through their client list “yesterday”. “If a building has not met the energy-efficiency requirements, it cannot be let and becomes economically unviable,” he says, adding that brokers need to look not just at clients with obvious “old stock”, but also those with mid-range properties.
Young continues: “One of the major construction companies pointed out the plethora of town-centre office buildings, those around 50 000 square foot. These will all need to be upgraded, and they will all need to be insured.”
However, it is not all about expensive changes and upgrades – there is some good news in relation to the legislation. Geoff Ball, a director at Cunningham Lindsey, believes insurers are helping lead the way. He says that while insurance costs may rise, they will not do so dramatically – and, in fact, some have already been absorbed by the construction industry.
“If we are involved in the reinstatement of a building we would have to comply with part ‘L’ of building regulations,” Ball says. “This means we would already be putting in much greater levels of insulation than we would have, say, 10 years back.”
Ball also reveals contractors on many building or reinstatement projects are achieving recycling rates of 92% – and have been for some time. He adds: “There are, of course, additional costs involved in the changes introduced [under the Energy Act], but from what we can gauge insurers have started to build this into their pricing. Insurers have, for some time, shown a desire to not just present a green image but also to actively adapt and promote energy saving measures.”
Ball says Climate Wise – the insurance industry’s global think tank on climate change – is a good example of an initiative helping insurers build energy efficiency into their business models. “For them, energy efficiency will be a win-win. The more efficient a building is, the cheaper premiums will be in the long run – and that is good for consumers and brokers.”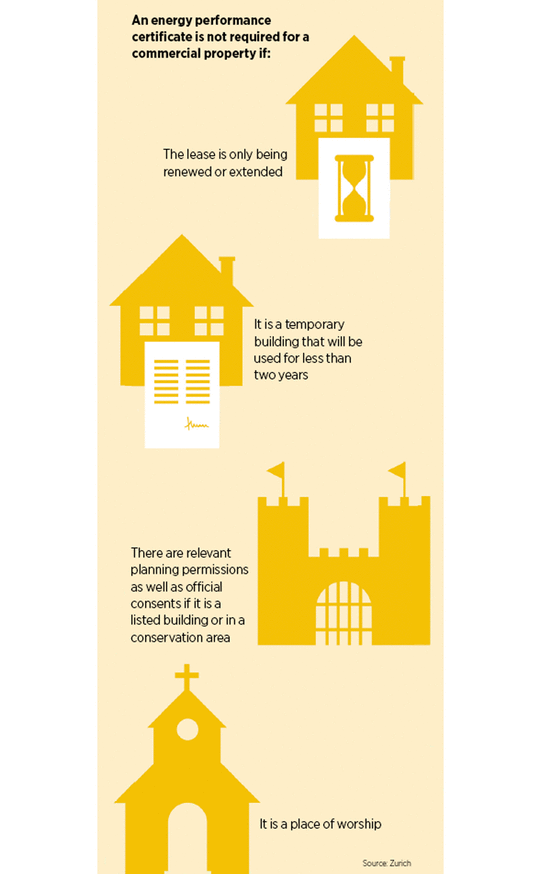
Much to do
However, there is still much work to be done. For example, Blanchard would like to see more insurers recognising green issues within their policy wordings, such as the green clause provided by Aviva. This offers help to policyholders who may be unaware of the extent of additional costs incurred by being energy efficient until the time comes to claim.
Aviva would not comment specifically on the Energy Act or its own green clause, but spokesman John Franklin says the firm is working to make sure its clients are not caught out by the act:”The legislation will mean properties will have to have a required level of thermal efficiency if they are to be rented out. Aviva provides specific cover for property owners that will reinstate a property to the required standard, even if at the time of the claim the property is below the level the legislation stipulates.”
For brokers, there are opportunities beyond advice –and Paul Cullum, product development manager at insurer HSB Engineering, says product innovation is already happening. “We have been writing energy-efficiency risk for many insurers and we’ve noticed a significant increase in the last year,” he says. “Interest in energy efficiency, rather than just its generation, is the real trend now.”
HSB insures the materials and equipment needed to make a building more energy efficient, and expects business to grow in the build-up to 2018 – so much so that it has launched a product that actually pays out if the measures do not result in the energy savings they were predicted to deliver.
As Cullum says: “For innovative businesses and brokers, the Energy Act is an opportunity that can benefit everyone.”
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@postonline.co.uk or view our subscription options here: https://subscriptions.postonline.co.uk/subscribe
You are currently unable to print this content. Please contact info@postonline.co.uk to find out more.
You are currently unable to copy this content. Please contact info@postonline.co.uk to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@postonline.co.uk
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@postonline.co.uk
More on Commercial
Allianz deal to bring Coalition to 15 markets by mid-2027
Coalition CEO Joshua Motta has told Insurance Post the firm’s partnership with Allianz will take it into 15 countries by the end of June 2027.
Allianz’s Lalwani on need for collaboration around AI governance
The insurance industry must work together to implement customer-centric artificial intelligence governance, according to Allianz UK’s chief data officer Akhil Lalwani.
Are insurers ready for autonomous vehicle crashes?
William Balfry, member of the motor sector focus team at the Forum of Insurance Lawyers and senior associate at DWF, examines the increasing rollout of automated passenger services and insurers will soon have to handle claims resulting from collisions.

KPMG’s Evans reveals US investors set to snap up UK insurers
US investors are lining up to buy mid and top-tier UK MGAs and brokers in the year ahead, according to Huw Evans, partner and head of insurance at KPMG UK.
Top 30 European insurers of 2026 revealed
Europe’s Top 30 non-life insurers achieved another year of solid top line growth in 2025, although exchange rate changes affected revenue negatively when converted to euros.
Time:To – Axa’s Crane on how to meet regulatory requirements
How artificial intelligence can be used to satisfy the Financial Conduct Authority is outlined by Mike Crane, managing director of Axa Commercial, in the latest Insurance Post Time:To video.

Axa outlines plan to drive organic growth and scale AI
Axa’s new strategic plan focuses on “accelerating customer-driven organic growth at attractive margins, and scaling AI to deepen our competitive moat”.
Diary of an Insurer: Zurich’s Paul Green
Paul Green, Zurich UK's multinational hub manager, engages with brokers, leads underwriters, enjoys river walks with his dog and late-night F1 racing sessions.