
Insuring the Birkin boom: risks in plain sight
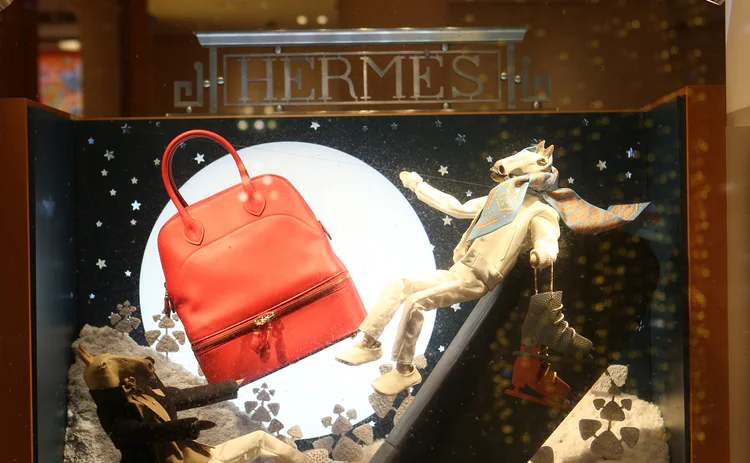
As iconic handbags appreciate significantly in value, Tim Evershed examines how insurers are adapting to challenges around portability theft risk, valuation volatility and the limitations of traditional home insurance policies to cover the cost of such expensive accessories.
In recent years luxury handbags have firmly established themselves as a serious alternative asset class.
Driven by scarcity, craftsmanship and global demand handbags produced by top fashion houses such as Chanel, Luis Vuitton and Gucci now fetch extravagant sums at sale and auction.
The coveted Hermès Birkin handbags have increased in value by 500% since 1981, at an average annual increase of 14.2% outperforming more traditional asset classes including gold, property and fine art, according to Chubb.
As with any high value item or collection, owners must ensure they have the appropriate insurance for their collection of designer handbags and, as values increase, so too does the importance of specialist advice, valuation accuracy and appropriate risk management measures.
Kevin Morton, head of Zurich Private Clients at Zurich UK, says: “Luxury handbags have firmly established themselves as a credible investment asset, with values rising by 85% over the past decade.
“As a high‑value asset class, their worth is driven by scarcity, craftsmanship and sustained market demand, all factors that demand careful consideration as values rise.
As a high‑value asset class, luxury handbags’ worth is driven by scarcity, craftsmanship and sustained market demand, all factors that demand careful consideration as values rise.
Kevin Morton, Zurich Private Clients
“With appreciation comes the need for specialist advice, ensuring valuations remain accurate, and appropriate protection is in place to minimise financial risk.
“This means helping clients apply accurate risk management to what is often an emotionally driven purchase from sourcing and authenticity, to preservation, storage and controlled use.
“Where protection is concerned, the weakness in most standard home insurance policies isn’t availability of cover, but suitability. Single article limits are often too low, and out‑of‑home cover is restricted unless specifically extended.”
Easy target
The insurance challenge of covering a high-value, luxury handbag is that it is essentially a highly portable, highly visible luxury asset. This makes them a relatively easy target for theft when their owners are travelling, shopping or dining out.
Alexandra Pattie, fine art and specie senior underwriter at Axa XL, says: “Most clients will be carrying these bags in busy urban areas, airports, shops, restaurants and hotels.
“There is, in all these scenarios a high possibility of the handbag being left unattended, being targeted for a theft and the possibility of accidental damage. Environmental factors can also have an effect as well as spills and scratches.
“As one would with fine art or other high valued items, they need to be handled with care and stored in a suitable and secure environment. Extra care should be taken when out in public to ensure the safety of the insured and the protection of the item.
“Homeowner policies can fall short with high deductibles, low individual item limits and restrictive terms. If the collection is of a certain size and value, we would always recommend specialist cover – similar to those that protect jewelery and other high value collections.”
Significant appreciation
Luxury handbags often appreciate significantly over time. Iconic bags from brands like Hermès and Chanel have soared in value, selling for much more on the secondary market.
The Hermès Birkin handbag starts at around £8,000 but is often priced far higher while its resale value is commonly two or three times the retail price.
With prices shifting quickly insurers and brokers face a significant valuation risk when arranging cover with underinsurance a threat.
Regular valuation updates, real‑time market data and flexible limits are all key to maintaining accurate cover.
Kelly Murray, claims manager for Aviva Private Clients, says: “Many luxury brands increase prices once or twice a year, meaning the amount a client originally paid can quickly become out of date.
“In the resale market, some iconic designs can even command prices above their original retail value, while limited production runs, waiting lists and discontinued styles can make like‑for‑like replacements difficult or impossible.
“Some items can also be gifted through families for generations, holding sentimental – as well as monetary – value.
“As a result, clients can find themselves vulnerable to the risk of underinsurance, which is why having up‑to‑date valuations for handbags and other high‑value items is crucial.
“Valuations confirm ownership, reflect current market values and can help speed up the claims process. They can also be the key to securing the right replacement.”
Aviva recommends clients have regular valuations, ideally every two to three years, to avoid the possibility of underinsurance.
The insurer works with a number of trusted valuers in order to support clients further.
In order to determine the value of a luxury handbag a proper assessment will examine factors like the condition of the fabric, leather and buckles, the brand, the age of the bag and the level of craftsmanship that went into creating it.
It will also consider it’s scarcity value as well as relevant receipts and authenticators. A professional evaluation will use all of these elements as a guide when working on assigning a value for a specific bag.
Alex Brice, senior underwriter for private clients at Brit, says: “These specialists have a detailed understanding of not just the replacement value of a handbag, but also the second-hand or ‘grey market’, where the value of items are often higher than the original purchase cost, due to the covetable nature of some of the unique editions of these bags.”
Mind the gap
Even with accurate valuations, experts warn there is the danger that gaps in coverage for high-value personal collections such as luxury handbags will be exposed.
Some policies will offer replacement, which is not always possible for limited edition items and some policies will offer agreed value or current market value.
Other areas that need to be understood by the insured will be in relation to exclusions and high deductibles.
All policies differ but unattended items, wear and tear, inherent vice, pest damage are excluded. Using a knowledgeable broker and insurer can help insureds better understand what is being covered and if the policy suits their specific needs.
Morton says: “The most common shortcomings in home insurance are structural rather than technical, with clients often assuming they have more protection than they do.
“Many believe a standard policy offers near‑unlimited cover, yet inner limits and off‑premises restrictions can materially reduce protection.
“Gaps also emerge where sums insured fail to keep pace with market values, particularly if policies lack index linking or automatic uplifts post‑valuation.
“Without these safeguards, cover can quickly fall behind the true value of a client’s assets. This is why broker engagement is critical, actively identifying gaps by aligning cover to how assets are used, stored, and intended to be held over the long term.”
There are also important gaps linked to policy conditions.
Higher-value items often trigger specific security requirements, including minimum standards for alarms, locks or storage arrangements.
If these conditions are not met, insurers may reduce or decline claims, even where the item itself has been correctly valued.
Documentation presents another challenge.
Clients must be able to demonstrate ownership, condition and authenticity through receipts, photographs and supporting evidence. Where this is lacking, claims can be delayed or only partially settled.
Brice says: “Handbags are accessories often worn out in the world and consequently they have become easily recognisable and highly theft attractive, not least due to the difficulties that are faced in acquiring some new handbags.
“As well as theft from the person, claims resulting for home burglaries have shown that designer bags have become as attractive as jewellery to thieves.
“Physical damage to these items is also an important consideration. For example, a water leak at home could result in significant damage to a designer handbag, requiring specialist cleaning and renovation.
“Being with an insurer that works with specialist third parties, who understand items such as these is vital. This will mean that handbags that are often very hard to replace, and may hold sentimental value, can be restored and returned to the client.”
Risk management
As with any high value item or collection, making sure the appropriate insurance is in place for designer handbags is the first step in a robust risk management strategy.
Prevention of loss is key so care must be taken when in public with the insured item while storing items in a stable environment with security suitable for the value concerned is also essential.
In addition, a combination of good recordkeeping and regular valuations from specialists are vital too.
Sara Bailey, head of private clients at Woodgate & Clark, says: “Start with accurate and regularly updated valuations, supported by independent assessments where appropriate.
“These valuations should then inform both the level of insurance cover and the security measures required to protect the assets.
“Storage is a critical component of this strategy. As values increase, so too do insurer expectations around how items are stored and protected.
“Ensuring that storage arrangements meet or exceed insurer requirements is essential, not only to safeguard the assets themselves but also to maintain the validity of the policy.
“Authentication and documentation should also be managed proactively. Maintaining a clear record of ownership, supported by receipts, photographs and authentication certificates, provides a strong foundation for both valuation and claims handling.
“For high-value or rare items, independent authentication can add an additional layer of assurance.
“When valuation, insurance, storage and documentation are brought together in this way, clients are better equipped to protect both the financial value and the integrity of their collections, while reducing the likelihood of disputes or shortfalls in the event of a loss.”
If insurers want to keep pace with the handbag boom, it is clear they must encourage owners to treat these items not just as accessories but as assets worthy of proper protection.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@postonline.co.uk or view our subscription options here: https://subscriptions.postonline.co.uk/subscribe
You are currently unable to print this content. Please contact info@postonline.co.uk to find out more.
You are currently unable to copy this content. Please contact info@postonline.co.uk to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@postonline.co.uk
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@postonline.co.uk
More on Personal
Prince William’s Earthshot finalists target climate risk solutions
Prince William’s Earthshot Prize finalists have been using insurance to help vulnerable communities manage climate risks, offering lessons for UK insurers looking to close the protection gap.
Phoebe Chibuzo Hugh to depart Monzo
Phoebe Chibuzo Hugh has revealed she is leaving Monzo after three years.
Penny Black’s Social Diary: Lockton locks-in with charity sponsorship
Penny Black has been out and about again, notebook in one hand and canapé in the other, keeping a keen eye on the insurance industry’s more whimsical moments.
Summer heatwave could cause pothole nightmare for insurers
Insurers could see a higher influx of vehicle damage claims and more complex liability investigations after this summer’s heatwave played havoc with the UK’s roads.
Allianz’s Lalwani on need for collaboration around AI governance
The insurance industry must work together to implement customer-centric artificial intelligence governance, according to Allianz UK’s chief data officer Akhil Lalwani.
Defaqto reveals new rating requirements
Defaqto has unveiled new rating requirements across personal lines in order for companies to retain three stars, under bold plans for 2027.
Are insurers ready for autonomous vehicle crashes?
William Balfry, member of the motor sector focus team at the Forum of Insurance Lawyers and senior associate at DWF, examines the increasing rollout of automated passenger services and insurers will soon have to handle claims resulting from collisions.
Insurance Compliance’s Allison questions insurance regulation
David Allison, head of intermediary consultancy south at Insurance Compliance, said improving customer understanding is an unsolvable problem, and questioned whether general insurance should ever have been regulated by the Financial Conduct Authority.