
Q&A: Fraser Edmond, Broker Insights
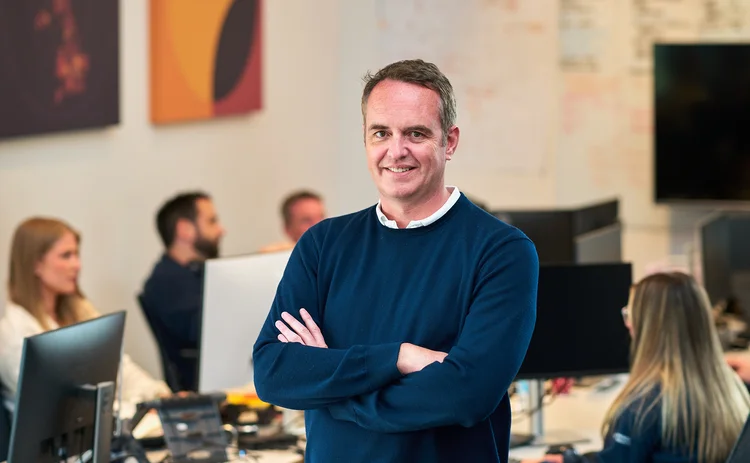

Broker Insights founder and CEO Fraser Edmond speaks to Insurance Post about the inefficiency of the commercial insurance space, bridging the knowledge gap between insurers and brokers, and how he hopes to more than triple the company’s coverage by the end of the year.
What brought about the idea for ‘Broker Insights’?
I was distribution director at Aviva, running all the sales and distribution teams, and what we could see was a really inefficient market within the commercial intermediated space.
It was inefficient because, as an insurer trying to distribute products to brokers, you need to understand the broker’s customer base, and without that knowledge, that’s pretty difficult.
Essentially what the business does is takes broker customer data from multiple brokers and populate a platform so you can interrogate to understand the market.
That’s where the business began and it has evolved over the last five years. So now, there are two clear problems that we’re solving: the understanding of the market that the insurers would love so they can allocate resources and distribute products more efficiently.
But equally, if you’re a broker, you often don’t know which market has an underwriting appetite for your customer.
What we do is we put our broker customer data, and our insurance risk appetite data together. Putting those two bits together, we then understand exactly which customers fit which insurer’s appetite.
For an industry that is very focussed on social relationships, how does the business fit in?
Insurance is a relationship-based industry but having information that bridges knowledge gaps, to complement existing relationships, is really powerful.
We have this conversation frequently. You can have the very experienced insurance brokers who have done 30 years, and pretty much know which market likes what type of risks.
But when they’ve got that 22-year-old member of staff who is in their team who has not got that acquired knowledge over time, having the insight that we provide sitting alongside them, can direct them much quicker and easier, and point them in the right direction. It is highly valuable in terms of efficiency.
For the insurers, a lot of business development staff have a good understanding of the market. They know roughly which brokers do what type of thing.
But they don’t know every single case and every single broker across the UK. If there was a platform that could tell them that information so that they can focus on where to spend their time and energy, then they can do a far greater job.
If you're a broker, you often don't know which market has an underwriting appetite for your customer
It is complementary knowledge. It is intelligence that sits alongside the existing market.
How much of the market have you accessed and signed up so far?
We’re actively signing up as much of the market as we possibly can.
In the time we’ve been doing this, we’ve signed up over £1.6bn of commercial GWP in the UK, across the small and medium-sized regional brokers. We have now started to sign-up some of the larger brokers as well.
We’re focused on effectively building this market knowledge in one place that’s highly valuable to both insurers and brokers.
Where has the service you provide shown the most value, and where have you been surprised to see it used?
If you’re in an existing relationship trading with a broker or insurer, you almost expect to know them but actually, there will be knowledge gaps.
So, the knowledge can enhance an existing relationship, but it’s definitely opening up new relationships, without a doubt.
Also, if people are not sitting alongside someone, learning from them every day, that’s going to naturally be more difficult if people are working remotely.
With the information and the knowledge being a complimentary thing, to build people’s knowledge and skills, then I think it also has a place to do that.
Can you give an example of how your services work?
It’s very much an efficiency game. So, if I’m a broker, and I’m looking to market my customer, or at renewal try to find a new price for them, I might send it to six different insurers, just to get two quotes back.
Unfortunately, if I’ve sent it to six insurers, and only two of them have got appetite for that risk, then I’ve wasted my time and the time of the four insurers that didn’t get back to me.
By having this appetite overlay combined with the customer data, you’re going to send it to three or four markets that are exactly the three or four markets that would absolutely have interest in that risk.
So you’ve just improved efficiency, and effectiveness massively, which, from a broker’s perspective, makes a trading relationship with an insurer far better, because they’re not wasting their time on stuff they don’t want to see.
What kind of businesses are you targeting?
When the business began, it was very much focused on small and medium, regional commercial brokers.
So that’s kind of where the business began but the data capability, the placement management capability, these component parts have huge appeal to larger brokers as well.
In the past 12 to 18 months, we’ve started to build out the proposition to those audiences as well. That’s becoming quite a strong part of our offence.
Now we’re able to hit all of the commercial broker market from micro small brokers right up to the largest national entities.
In terms of insurers, again, it’s got a broad appeal to insurers. If you’re looking to distribute your products to the broker market, knowing the market understanding the market and efficiently, being able to engage with the market is much more efficient than it would have been without this.
The partners that we’ve had since we started the business, the growth that they’ve achieved through ourselves is significantly stronger than what they achieved with that standard approach to market.
Where are insurers and brokers going wrong when it comes to placing business?
I think the key thing on the broker side is insurer appetites are changing all the time. What you get is an insurer might decide to dial down on their motor account at the same time as they dial up on their liability. It’s not a static position.
So knowledge becomes outdated quite quickly. But, actually, it is not outdated, insurers just consciously decide to dial up its appetite in one place, and not another. That’s why that bit is valuable.
From an insurer perspective, genuinely just understanding what the market looks like, how it’s constructed, where it all lives, and being able to align your sales and distribution and trading resources to where the opportunity lies.
There’s no point in having your resources pointing at brokers that don’t have any of the business that you actually want to write. It sounds so obvious, but actually, without that knowledge, how do you do that?
What are you seeing in the commercial space at the moment in?
I can’t talk specifics, but we can see what’s going on with rates.
We know who is winning and who is losing in terms of who is writing business, who is losing business - we've got all that knowledge.
We've got sentiment knowledge. We can see who is supporting what insurers, and which insurers are not receiving support.
When we started the business, we didn't foresee the value, or the volume, of this insight that sits around the edges of the core piece. But there's a lot of sentiment stuff, and trading market knowledge that we can share.
What is your trajectory plans for the business going forward?
We cover £1.6bn of commercial GWP at the moment, coming from about a couple of hundred small and medium sized brokers, in roughly 500 offices.
What we have started to do is push into the larger brokers. We have signed effectively what we call an enterprise solution, which is where we give a version of the platform to larger brokers and make it configurable to some of their needs.
We did the first one of those with Clear Group about 12 to 18 months ago, and we have been really successfully working with them expanding out the capability.
We've also signed Partners& onto that, so they've got their own version. We've got a couple of quite big announcements to come out in the next few weeks, another couple of really big brokers. That will take us up to about £2.3bn.
And now, some of the plans that we've got in our sights for this year, is we would like to get close to £4bn to £5bn of commercial GWP by the end of the year.
That's based on our current pipeline of activity, and the reason that's kicking up so much is because we're starting to talk to larger broker entities. We've quietly been building that position. We've not shouted about it too much until now.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@postonline.co.uk or view our subscription options here: https://subscriptions.postonline.co.uk/subscribe
You are currently unable to print this content. Please contact info@postonline.co.uk to find out more.
You are currently unable to copy this content. Please contact info@postonline.co.uk to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@postonline.co.uk
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@postonline.co.uk
More on News
John Lewis Money hires former Co-op Insurance boss
Former Co-op Insurance managing director Charles Offord has been hired by John Lewis Money as director of financial services, as the business looks to develop its broker model for credit and insurance.
Tokio Marine HCCI launches humanoid robot coverage
Tokio Marine HCC International and broker Adrian Flux are launching what they describe as the UK’s first domestic humanoid robot household insurance policy.
OpenAI reveals ‘strength and depth’ of security insurers need
Viyat Bhalodia, a member of the technical staff at ChatGPT creator OpenAI, has outlined the security controls insurers need when using artificial intelligence agents.
Insurance sector reponds to 2026 Budget
John Healey has delivered his first Budget as Chancellor of the Exchequer today (28 October), bringing in a range of changes for SMEs and UK businesses, but notably failed to act on Insurance Premium Tax rates.
Zurich’s Matthias says EU climate alliance is a ‘shared priority’
The European Union will establish a Climate Insurance Alliance, which will deliver actions to narrow the climate protection gap as Zurich’s Resilience Solutions’ global head, Robin Matthias, said the scheme was an opportunity for public-private co-operation.

Lloyds Bank picks Superscript for SME insurance
Lloyds Banking Group has selected digital insurance broker Superscript to provide business insurance to its small business customers.

Guidewire eyes AI agents as consumers of platform
Guidewire is “starting to think about AI agents as sort of first-party consumers of this platform,” according to CEO Mike Rosenbaum.
Guidewire pays £1.2bn for Hyperexponential
Guidewire is set to buy Hyperexponential for $1.7bn (£1.27bn), with $400m (£300.05m) more payable if recurring revenue targets are hit, as it looks to ‘define’ the use of artificial intelligence in underwriting.