
This article was paid for by a contributing third party.

Q&A: Kumar Utpal, Decerto
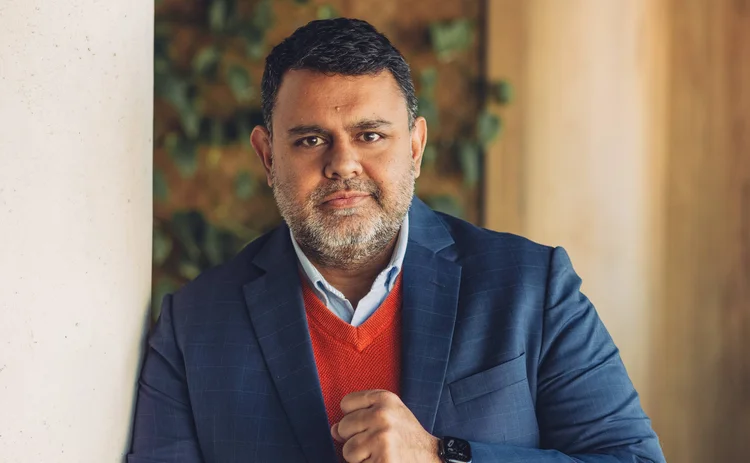
Kumar Utpal, head of business development at Decerto, explans how insurers can use AI to beat the fraudsters at their own game, meet Consumer Duty requirements and make more consistent claims decisions.
UK insurers detected fewer fraudulent property claims in 2025, but the average value reached a record of £11,400. What is driving that shift, and how is AI changing the fraud landscape?
Fraudsters are submitting fewer claims, but they are targeting larger payouts. In 2025, insurers detected 17,700 fraudulent property claims, down 6.2% year-on-year, yet the average value rose to a record £11,400 per claim. At an industry level, insurers detected £1.34bn of insurance fraud, a 14% increase on the previous year.
The Association of British Insurers itself describes this as fraudsters “targeting much bigger payouts”. In our view, a few factors are likely contributing. Higher repair and rebuild costs raise the value of every property claim, including fraudulent ones.
The Association of British Insurers itself describes this as fraudsters “targeting much bigger payouts”. In our view, a few factors are likely contributing. Higher repair and rebuild costs raise the value of every property claim, including fraudulent ones.
A larger share of detected cases appears to involve deliberate, well-prepared fraud rather than small opportunistic exaggeration, and those cases tend to be worth more. It is also worth remembering that these are detected cases: a fall in volume can reflect changes in how and where insurers focus their detection, not only a fall in fraud itself.
At the same time, generative AI is making it easier to create convincing photos, documents, and supporting evidence. However, insurers can use AI themselves to identify anomalies, suspicious patterns and hidden connections across claims, enabling investigators to focus on the cases that present the greatest risk.
Generative AI is making it easier to manipulate images and documents. How can insurers continue to trust digital evidence?
Digital evidence should never be reviewed in isolation. A photograph may appear genuine, but it needs to be validated against policy records, claim history, repair estimates and other supporting information.
Insurers need to assess evidence within the wider claim context, highlighting inconsistencies and potential red flags. This provides claims handlers with a more complete picture and supports more confident decision-making.
How can insurers strengthen fraud controls without slowing down genuine claimants, particularly under Consumer Duty requirements?
Consumers expect fast, fair, and transparent claims handling, while insurers need effective fraud controls. The challenge is balancing both.
To do this we would recommend insurers risk-score and triage claims at first notification of loss.
Low-risk claims can move through the process more quickly, while complex claims, or claims showing indicators that require investigation, are referred for further review.
This improves customer experience while ensuring investigative resources are focused on where they deliver the most value.
Many home insurance disputes arise from policy interpretation rather than fraud. How can AI help insurers make more consistent claims decisions?
Home insurance continues to show lower claims acceptance rates than motor insurance: 62% for buildings and 71% for contents and combined buildings and contents cover in 2025, compared with 99% for motor, according to the Financial Conduct Authority’s general insurance value measures data.
AI can support consistency by identifying the policy provisions, exclusions and conditions relevant to each claim. Such decision support and reasoning helps handlers apply policy wording more consistently while retaining full human oversight.
This can improve transparency, reduce disputes, and support Consumer Duty objectives.
Beyond fraud detection, how can AI help home insurers reduce claims costs and move towards prevention?
The biggest opportunity for insurers is beyond fraud. Claims leakage, overpayments, inconsistent settlements and avoidable losses can all impact profitability.
AI can helps insurers identify cost anomalies, improve settlement consistency, and streamline routine reviews. In addition, by analysing claims patterns and property risk indicators, insurers can identify properties at higher risk of future losses, such as escape of water or storm-related damage.
The long-term goal is not simply processing claims more efficiently but preventing losses from occurring in the first place. That creates better outcomes for insurers and policyholders alike.
The future of AI in claims is not just about finding fraud. It is about helping insurers make faster, fairer and more consistent decisions while reducing avoidable losses across the entire claims lifecycle.
Kumar Utpal is head of business development responsible for Decerto Claims AI proprietary product
Sponsored content
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@postonline.co.uk
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@postonline.co.uk